Dubai luxury property 2026 entered the final quarter with a striking but easily misunderstood signal. A DLD-based market analysis published on 27 September counted 335 home sales above US$10 million, equivalent to roughly AED 36.7 million, during the first eight months of 2026. That is evidence of a functioning global trophy-home market. It is not evidence that every villa, penthouse or branded residence deserves an ultra-prime valuation.
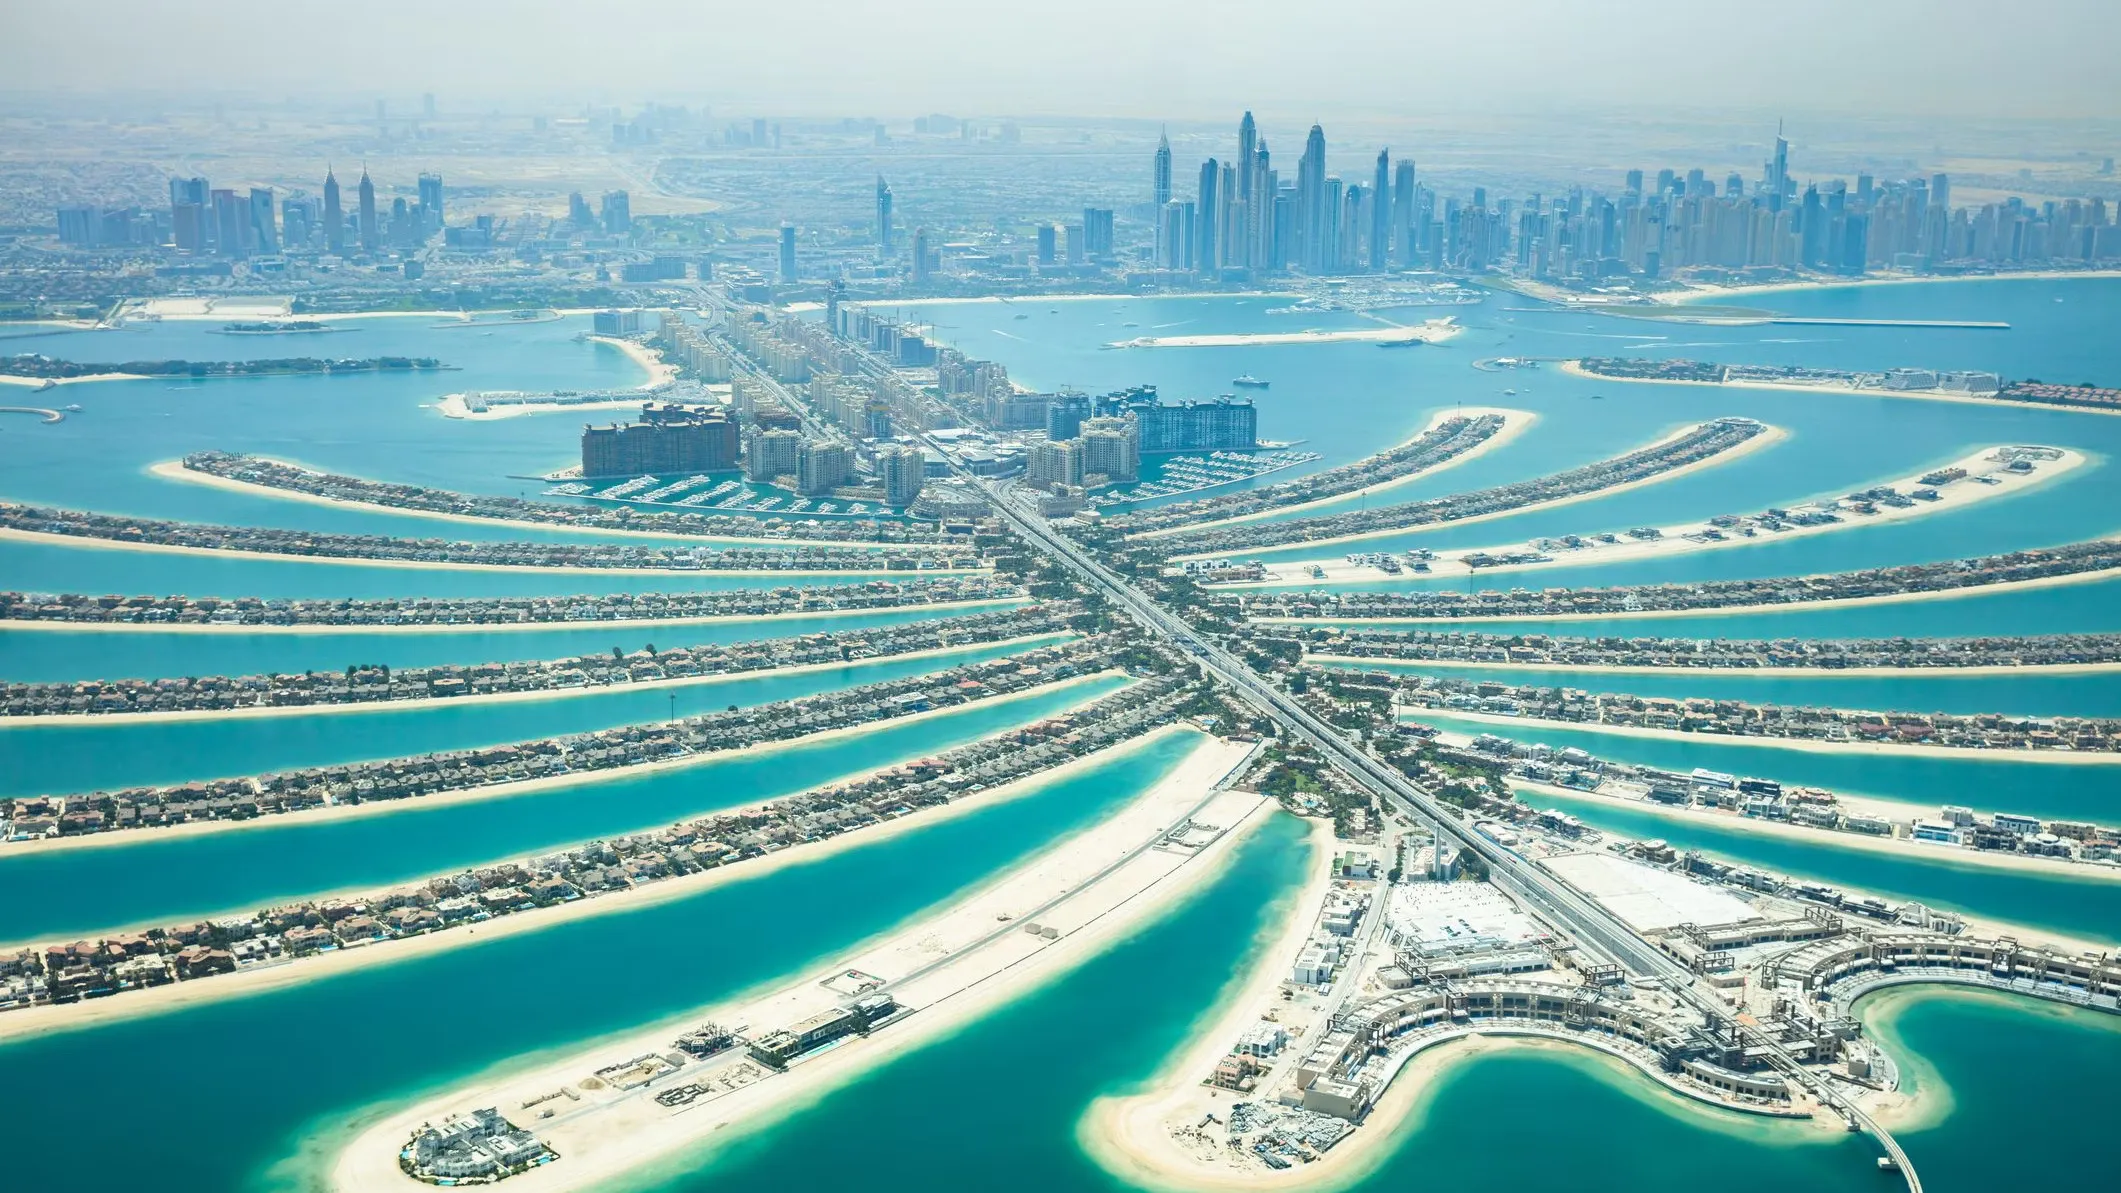
The reported total divides into 206 villa transactions worth AED 11.7 billion and 129 apartment transactions worth AED 8.67 billion. Those figures imply an average of about AED 56.8 million per recorded villa and AED 67.2 million per recorded apartment, although averages can be distorted by a small number of exceptional deals. Palm Jumeirah remained among the top three districts for both villa and apartment deals by volume and value. Source: Khaleej Times analysis of Dubai Land Department data, 27 September 2026.
The context is more selective than the headline suggests. Separate second-quarter reporting counted 38,257 Dubai property transactions worth AED 110.36 billion, while transaction volume was reported 28% below the corresponding 2025 period. Branded-residence transactions in the first half of 2026 were reported down 21% by volume and 47% by value to US$6.02 billion. That combination—large trophy transactions alongside softer wider volumes—is precisely why buyers need asset-level analysis rather than a simple bullish or bearish label. Source: The National, 9 September 2026, citing DXB Interact and Morgan's International Realty.
Why it matters for Dubai luxury property buyers
Ultra-prime demand is not one market. A beachfront frond villa, a completed serviced apartment and an off-plan penthouse occupy different liquidity pools. Villas offer land, privacy and a scarce shoreline position. Apartments can deliver views, security and hotel-level services, but the buyer must compare usable internal area, terraces, lift access, floor plate, service charges and the number of competing branded schemes due at handover.
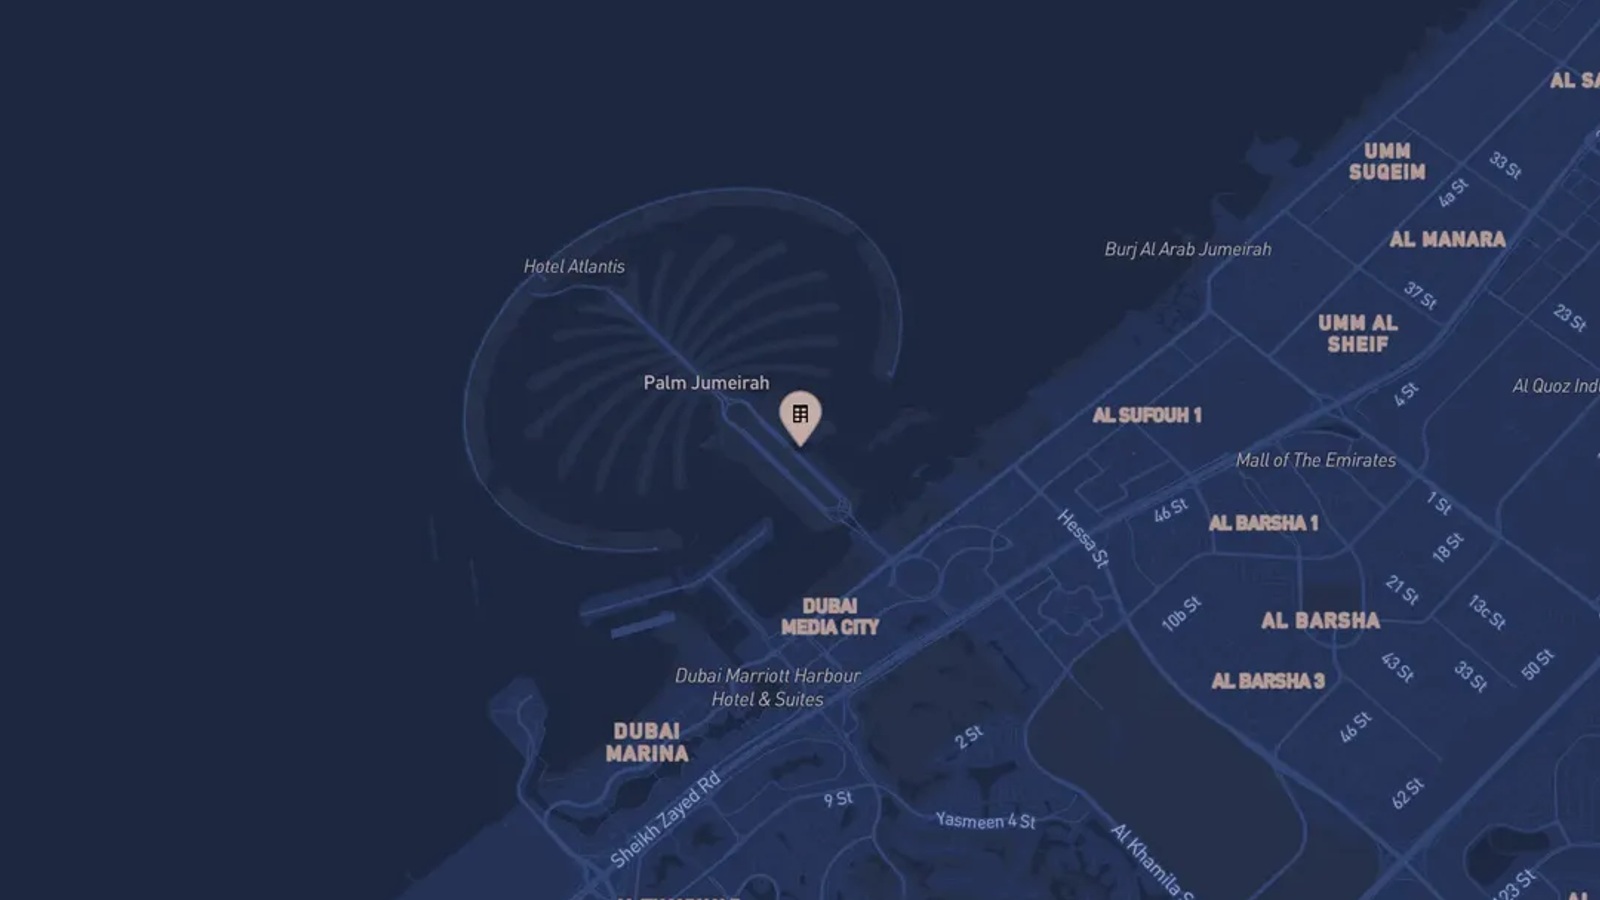
The GenieMap Como Residences project visual used here places the discussion on Palm Jumeirah, where location scarcity is real. GenieMap lists Como Residences as an off-plan Nakheel project with a September 2027 handover indication and a starting price input of AED 49 million for the displayed inventory. Those are project-directory inputs to reconfirm, not a valuation or availability promise. The image is geographic project context and does not depict a specific unit offered by Astraterra.
At Astraterra, we find serious luxury buyers ask three different questions: Is the address globally recognisable? Is this exact unit difficult to replicate? Can the exit market absorb it without a large discount? The first question attracts attention; the second and third determine whether the purchase behaves like a trophy asset or merely an expensive apartment.
Joseph's Take
I would not use the 335-deal headline to justify paying any asking price. I would use it to confirm that Dubai has a deep high-net-worth buyer pool, then negotiate from completed evidence. In our current advisory work, the decisive differences are the view corridor, privacy, layout, arrival experience, parking, management cost and how many similar units can be offered at the same time. Scarcity must be demonstrated at unit level.