What the 7.5x Dubai office price spread means
Written by
Joseph Toubia
Founder & RERA Certified Real Estate Agent | Astraterra Properties Dubai
Commercial property adviser, BRN 54738
Quick answer
Offices for sale in Dubai should be compared on effective usable cost, building quality, tenant demand and exit liquidity—not citywide price per square foot. A wide 2026 asking-price spread creates opportunity, but the cheapest district can become expensive after fit-out, vacancy, service charges and resale friction.
Offices for sale in Dubai reportedly showed a roughly 7.5x difference in average active asking price per square foot between the least and most expensive qualifying districts in a market scan published on 28 September 2026. That is a useful signal, not a valuation certificate. Asking stock can mix fitted and shell-and-core offices, whole floors and small suites, vacant and tenanted units, premium views and compromised layouts.
The practical lesson is that “Dubai office price” is not one market. A Downtown Dubai suite near key hospitality and financial demand, a Grade A DIFC office, a Business Bay strata unit, a JLT office beside a Metro station and an International City commercial suite serve different occupiers and exit pools. Comparing their asking prices without adjusting for net usable area, fit-out, parking, service charges, vacancy and building performance can produce false bargains.
The broader 2026 market is undeniably active. Gulf News reported AED 38.0 billion of Dubai commercial transactions across 3,622 deals in Q1 2026. Khaleej Times reported H1 2026 Dubai property sales of AED 286.43 billion across 79,229 transactions. Those figures establish liquidity and confidence at city level. They do not prove that a specific office will lease at the broker's estimate or resell at the seller's target.
Key takeaways
Area averages are a screening tool, not an offer price.
Effective usable cost matters more than saleable-area price.
Existing tenant quality can be more valuable than a glossy fit-out.
Parking, lifts and access shape both rent and resale liquidity.
A complete commercial brief comes before a shortlist.
Joseph's Take: buyers often send me two listings and ask why one office costs much more per square foot. The answer is rarely just the district. We look at the tower, exact stack, efficiency, natural light, lift waiting time, parking allocation, title, tenant covenant, lease expiry, service-charge history and realistic buyer pool. The lower price becomes irrelevant if the unit needs a major fit-out and sits in a building occupiers avoid.
The contrarian view is that a high price per square foot can sometimes be the lower-risk purchase. A smaller, efficient office in a liquid building may require less capital, lease faster and attract more end-user buyers than a large discounted suite with unusable corners. Equally, a secondary district can outperform a prime postcode when acquisition price, service charges and tenant demand are aligned. Value is the relationship between total cost and durable demand, not the lowest number in a spreadsheet.
How to compare Business Bay, JLT, DIFC and emerging office districts
How to compare Business Bay, JLT, DIFC and emerging office districts
Business Bay offers the widest spectrum: older strata towers, newer premium buildings, canal-facing suites, fitted offices and off-plan commercial launches. Micro-location matters between Marasi Drive, Bay Square, Executive Towers and the Sheikh Zayed Road edge. Check vehicle access at peak time, visitor parking, lift performance, the mix of licensed activities and whether the building's management supports the target tenant profile.
Jumeirah Lake Towers combines Metro access, free-zone demand, restaurants and a large resident catchment. Yet Almas Tower, Uptown Dubai and individual lake clusters are not interchangeable. Walk the route from the Metro, inspect visitor access, count parking spaces and examine the view and heat load. A competitive JLT price can be compelling, but only when the tower and unit match the future tenant.
DIFC and Downtown Dubai carry stronger address premiums and a deeper pool of finance, professional-services and prestige-led occupiers. The acquisition cost and fit-out standard can be materially higher. Buyers should test whether expected rent compensates for the capital committed and whether the unit can compete with institutional-quality supply. A trophy address does not excuse weak efficiency or an unrealistic rent assumption.
International City, Dubai Silicon Oasis, Dubai Investment Park and other emerging or value-led districts may offer lower entry points and proximity to specific business clusters. The opportunity is highly use-dependent. A logistics-support company, back office, medical administration business and client-facing wealth manager do not value the same location. Start with the likely occupier, then test the building—not the other way around.
2026 supply makes building selection more important
Knight Frank mapped approximately 24.2 million sq ft of Dubai office pipeline from 2026 to 2030, including about 4.6 million sq ft in Business Bay, 3.8 million sq ft in Meydan City and 3.4 million sq ft in DIFC. CBRE separately projected roughly 400,000 square metres, about 4.3 million sq ft, of UAE office completions across 2026 and 2027. These estimates use different scopes, but both reinforce the same point: future competition will be building-specific.
New supply is not automatically bearish. Modern offices can attract new firms, lift district quality and establish higher rental benchmarks. But an older tower with slow lifts, limited parking and dated common areas must compete either on price, location, efficiency or a defensible tenant niche. Buyers should inspect competing deliveries scheduled before their intended exit and ask who will occupy them.
A GenieMap example: Tomorrow Commercial Tower
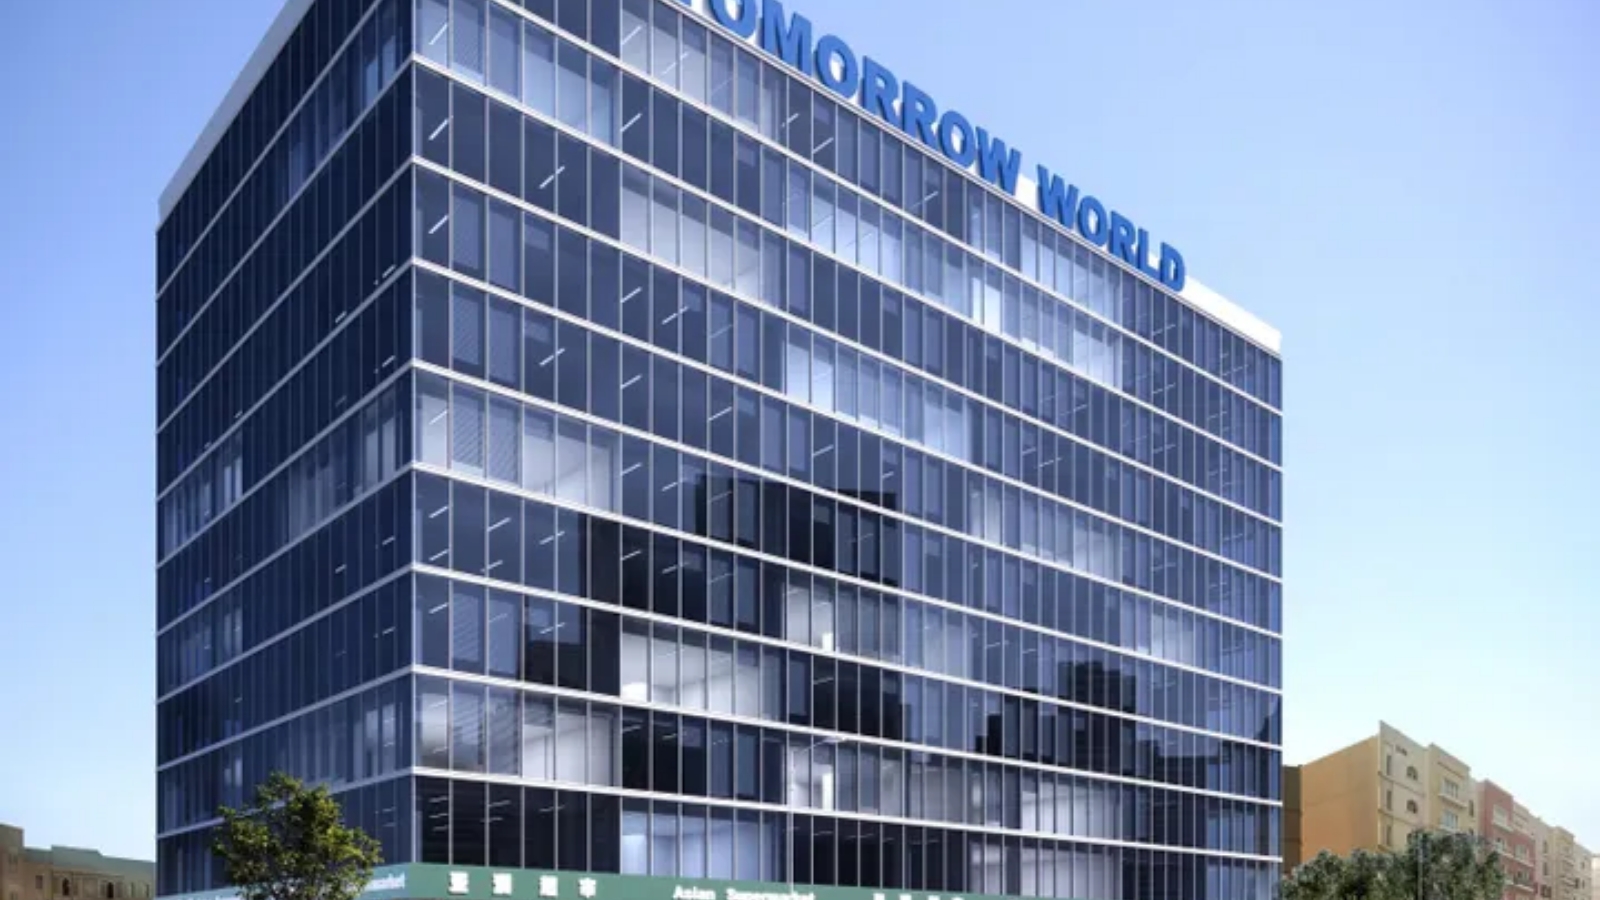
GenieMap's project record for Tomorrow Commercial Tower in Dubai International City showed a starting price near AED 1.9 million. Treat that figure as a dated project example requiring reconfirmation, not live inventory or a recommendation. It illustrates the underwriting question: does a lower-entry commercial project offer enough specification, access and future tenant depth to compensate for location and delivery risk?
For any off-plan office, verify the developer, escrow status, registration, payment schedule, handover definition, permitted assignment, parking, service-charge estimate, fit-out condition and what counts as saleable versus usable area. Review floor plates, columns, washrooms, pantry provision, power and cooling. A payment plan improves cash timing; it does not guarantee completion, rent, capital growth or resale liquidity.
Compare the project against ready alternatives using the same holding period. Include the opportunity cost of instalments, fit-out after handover, snagging, vacancy, finance, DLD and trustee charges, agency fees and expected sale costs. Then stress-test rent 10% below the optimistic case and handover later than scheduled. If the investment works only under perfect assumptions, the apparent discount is not enough.
Office buyer checklist, FAQs and CRM-qualified enquiry
Offices for sale in Dubai: the 2026 buyer checklist
Begin with a written brief: buy, invest or occupy; business activity; preferred districts; total budget; finance status; minimum usable size; fitted, semi-fitted or shell-and-core preference; parking requirement; free-zone or mainland licensing needs; expected occupancy date; and intended holding period. This filters incompatible units before viewings and lets an adviser compare like with like.
For ready property, verify title, seller authority, existing lease, rent receipts, deposit, notices, service-charge statement, outstanding balances, parking allocation, floor plan, measured usable area, permitted use, fit-out approvals and building rules. Inspect at a working-hour peak. Speak with management about access, lifts, air-conditioning hours, deliveries and planned capital works.
For investment, calculate net income after vacancy, incentives, management, maintenance, service charges, insurance and acquisition costs. Do not describe gross rent divided by purchase price as the final yield. For occupation, compare ownership cost with a realistic lease, including fit-out capital and flexibility. A business that may double headcount can value lease optionality more than ownership.
Frequently asked questions
Is the cheapest office price per square foot the best value?
No. Adjust for usable efficiency, fit-out, parking, service charges, vacancy, building quality and realistic exit demand.
Which area is best for an office investment in Dubai?
There is no universal winner. Business Bay, JLT, DIFC, Downtown Dubai, Dubai Silicon Oasis and International City serve different tenants, budgets and licensing needs.
Should I buy a fitted or shell-and-core office?
A fitted unit can reduce opening time, but only if the layout and approvals suit the occupier. Shell-and-core provides control while adding cost, delay and execution risk.
Can an off-plan office be easier to finance?
A developer payment plan may stage cash calls, but bank lending, assignment and resale rules vary. Verify the full terms and maintain a contingency.
What documents should an office investor review?
Review title or project registration, seller authority, lease, service-charge history, floor plan, parking, approvals, payment schedule and relevant building-management records.
How does Astra Terra shortlist offices?
We qualify intent, activity, area, budget, size, fit-out, parking, permissions and timeline, then compare the unit's total cost and tenant or occupier fit.
Send a commercial brief for a qualified shortlist
Use the commercial enquiry form on this page to send your name, phone or email, buy or invest intent, office activity, target area or project, budget, size, fit-out preference, parking or permission needs and timeline. Astra Terra Properties can then screen relevant ready and off-plan office options instead of sending an unqualified inventory dump.
You can also review our commercial property for sale in Dubai guidance and off-plan commercial projects in Dubai, or contact Astra Terra Properties for a RERA-certified consultation.
Disclaimer: This content is for informational purposes only and does not constitute financial, investment or legal advice. Market figures and project terms cited for 2026 must be independently reconfirmed before any transaction. Prices, rents, availability, service charges, payment plans and returns can change. No yield, appreciation or occupancy is guaranteed.
WhatsApp brief: send your office requirement to Astra Terra Properties.